A plumbing truck breaks down on a Thursday. You pay for the repair from the same account that covers groceries, a family streaming subscription, payroll, and customer deposits. By Monday, you cannot tell whether the business had a profitable week or whether the bank balance is simply hiding a pile of bills. That is exactly why learning how to separate business finances matters for a growing home service company.
Keeping business and personal money apart is not about making your life more complicated. It is about knowing what your company can afford, paying the right taxes, protecting your records, and making decisions with facts instead of a quick glance at the checking account. For busy contractors, that clarity is worth a lot.
Why mixed finances cause expensive confusion
When personal and business transactions run through the same accounts, every bookkeeping task takes longer. Someone has to sort fuel purchases from family errands, identify whether a hardware-store charge was for a job or a home project, and decide how to record cash moved between accounts. The mess tends to grow quietly until tax time, when it becomes urgent.
Mixed finances can also hide operational problems. A healthy bank balance may look reassuring, but it does not tell you how much belongs to payroll, sales tax, a supplier invoice, or your own owner pay. Likewise, a low balance may not mean the company is failing if a large customer payment is due tomorrow. Clean financial records separate those realities.
For incorporated businesses and LLCs, separating funds also supports the legal distinction between you and the company. That distinction is not a magic shield, and the details depend on your entity and state law. Still, consistently treating the business like a business is a smart habit. It gives your accountant, lender, insurance provider, and tax preparer a much clearer picture of how the company operates.
How to separate business finances in a practical order
The goal is not to create ten new accounts and another pile of administrative work. Start with a simple system that matches the way your business collects money, pays people, and buys materials.
Open a business checking account
Use a checking account in the legal name of your company for customer payments and business expenses. Deposit checks, card payments, financing proceeds, and other business income there. Pay vendors, subcontractors, software subscriptions, insurance, fuel, and operating costs from that account.
If you are a sole proprietor, this step is still worth taking even though you and the business are not separate legal entities. A dedicated account gives you a clean record of income and expenses. It also stops personal spending from blending into the transactions your bookkeeper needs to review.
Choose an account with features that fit your operation. Contractors who make frequent cash deposits may care more about branch access and deposit limits. A service business that collects most payments electronically may prioritize integrations and low transaction fees. The best choice depends on how money actually moves through your company.
Get a business card for business purchases
A dedicated business credit card or debit card prevents a common source of bookkeeping cleanup: the owner who pays for every supply run, lunch meeting, and recurring software bill on a personal card.
Use the business card for legitimate business expenses only. Keep personal spending on your personal cards, even if you plan to reimburse yourself later. A card is also useful when technicians need controlled purchasing access. Rather than handing out your personal card, establish clear spending rules, receipts requirements, and approval limits.
Credit cards are not free cash. If you carry a balance, interest can turn routine expenses into a profit leak. The practical move is to use a card for recordkeeping and cash-flow timing, then pay the balance from the business checking account according to a plan you can sustain.
Set up separate savings buckets
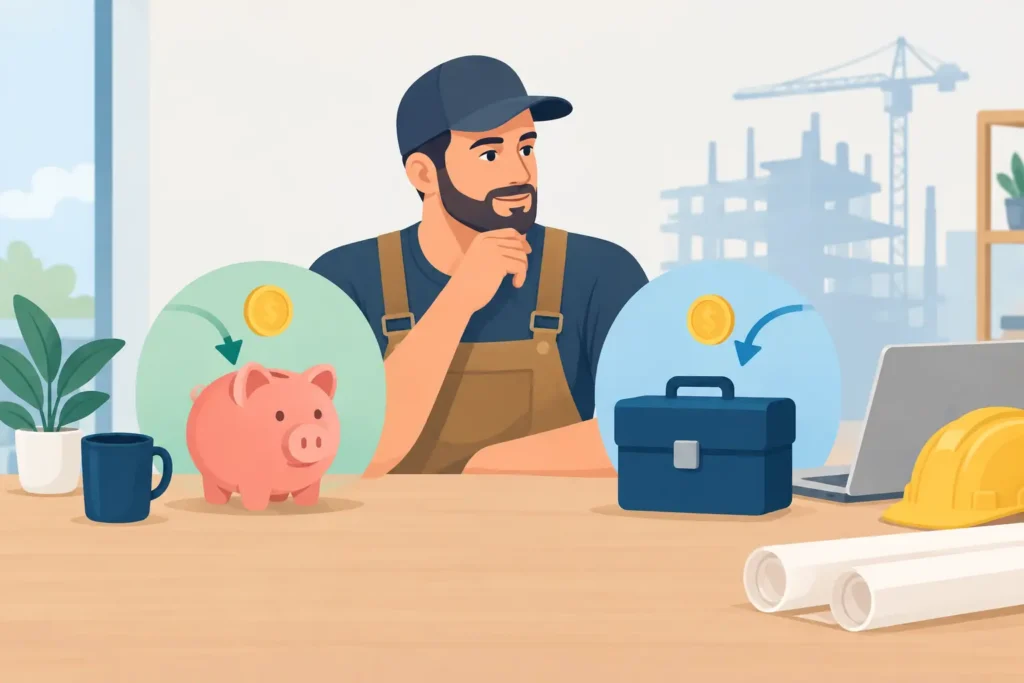
A checking account handles day-to-day activity. Savings accounts protect money that is already spoken for. Many home service owners benefit from separate buckets for taxes, payroll reserves, equipment replacement, and slow-season cash reserves.
You do not need a perfect percentage on day one. Start by reviewing your recent financials with a tax professional or bookkeeper. Your tax reserve depends on your entity type, profitability, payroll, state obligations, and other factors. Sales tax collected from customers is not extra revenue to spend. Set it aside promptly so the filing deadline does not bring an unpleasant surprise.
Payroll deserves special attention. If you have employees, keep enough cash available for wages, employer taxes, and benefits. Paying the team on time is not optional, and using money earmarked for payroll to cover a new truck down payment can create a painful scramble.
Pay yourself intentionally
Owners often blur finances because they take money from the business whenever they need it personally. That makes it difficult to measure profit and nearly impossible to build a predictable household budget.
Instead, establish a regular owner-pay process. The correct method depends on your tax structure. An owner of an S corporation may need reasonable compensation through payroll, while a sole proprietor commonly takes owner draws. Do not guess here. Confirm the right treatment with your tax advisor.
The important operational rule is simple: transfer money from the business account to your personal account with a clear memo and a consistent process. Do not pay personal rent, groceries, vacations, or credit card bills directly from the business account.
Handle the transactions that do not fit neatly
Real businesses have exceptions. You may accidentally use a personal card for an emergency part on a Sunday. You may cover a business expense personally while waiting for a new account to open. These events do not ruin your books, as long as they are documented and corrected.
Save the receipt, note the business purpose, and record the transaction as an owner contribution, employee reimbursement, or other appropriate entry. Then reimburse yourself from the business account when appropriate. What creates problems is not the occasional mistake. It is leaving dozens of unexplained charges for someone to untangle months later.
The same idea applies when you put personal money into the business. Record it clearly rather than calling it income. If you take out a business loan, keep the loan proceeds and payments properly tracked. Accurate categories matter because they shape your profit reports and tax returns.
Build a weekly routine that keeps the system clean
Financial separation succeeds when it becomes routine, not when you make one heroic cleanup effort in April. Set aside a short weekly window to review transactions, upload receipts, approve bills, and confirm customer deposits. If you use field-service software, make sure payment activity is flowing into the books in a way your team can verify.
At month-end, reconcile the checking, savings, and credit card accounts to the statements. Reconciliation is where missing payments, duplicate charges, and old uncleared checks surface. Then review a profit and loss statement, balance sheet, and cash-flow information that reflect the real condition of the company.
For many owners, this is the point where professional bookkeeping earns its keep. A dedicated bookkeeper can organize transactions, maintain your chart of accounts, collect the documentation needed for clean records, and flag questions before they become year-end surprises. YetiBooks works with home service companies because a contractor’s financial workflow is different from a generic retail business or office-based firm.
Watch for signs your separation system needs work
If you do not know how much cash is available after payroll, taxes, and bills, your accounts may be organized but not yet managed. If receipts live in truck consoles, text threads, and glove boxes, the recordkeeping process needs a simpler handoff. If you wait until tax season to categorize a year’s worth of transactions, the system is asking too much of you.
Another warning sign is relying on the bank balance as your only scorecard. Your bank account tells you how much cash is there at one moment. It does not tell you which services are most profitable, whether labor costs are rising, or whether your jobs are producing enough margin to support growth.
Cleanly separated finances give you the foundation for those answers. Once business activity is no longer mixed with personal spending, your reports can show what is really happening in the field and in the office.
The next time your company has a strong month, do not let that money disappear into a blur of personal and business transactions. Give every dollar a clear home, keep the records current, and let your financials do what they should: help you run the business with more confidence and less guesswork.